When a business starts accepting payments from its customers over the internet, the initial need is usually clear: to facilitate the payment process and accelerate collection. However, as the number of customers, transaction volume, and dealer network grow, new questions arise. Which customer's payment has been completed? Which dealer's debt has been cleared? Have the collected amounts been transferred to accounting records? Can transactions across different banks be tracked from a single place?
These questions highlight the fundamental difference between a virtual POS and an online collection system. Virtual POS is the infrastructure that enables card payments to be executed. An online collection system, on the other hand, is a broader structure that encompasses not only receiving payments but also tracking collections, managing customer and dealer relationships, reporting, and integrating with accounting processes.
So, in which situations can businesses proceed with a virtual POS, and in which situations do they need a comprehensive online collection system? To understand the difference, it is necessary to first look at what the two solutions offer.
What is Virtual POS?
Virtual POS is a payment acceptance infrastructure that allows businesses to receive payments online via credit or debit cards. It can be thought of as the digital equivalent of a physical POS machine. The customer enters their card information on the payment screen, the transaction is processed through the relevant payment infrastructure, and the transaction result is transmitted.
For example, a business selling products online can use a virtual POS to collect order payments from its customers. Once the customer completes the payment process, the business can check the status of the payment through the transaction details provided by the infrastructure it uses.
The primary function of a virtual POS is to execute the payment transaction. However, a business's collection operation does not always end with payment approval. Processes such as identifying which customer or dealer the collection belongs to, associating it with the relevant receivable, updating accounting records, and preparing financial reports must also be managed.
These operations can vary depending on the scope of the virtual POS used, the business's existing software, and the integrations it has established. For a business that only needs to receive payments, a virtual POS may be sufficient. For businesses working with multiple banks and a large number of customers, however, it becomes crucial to manage collections alongside other financial processes.
What is an Online Collection System?
An online collection system is a software solution that enables businesses to receive payments from their customers, dealers, sub-dealers, or subscribers via digital channels and to manage collection operations through a centralized structure.
Virtual POS, payment institutions, or other supported payment methods can be used within these systems. However, the function of the system is not limited to merely initiating or completing the payment process. Who the collection was made from, which transaction it is associated with, and how it will be tracked in financial processes are equally important.
Depending on the scope of the online collection system, businesses can run the following operations through a single structure:
Multi-payment infrastructure management: Integrating the virtual POS infrastructures of multiple banks or payment institutions to manage collection transactions from a central point.
Dealer and customer tracking: Tracking collections from different customers and dealers, providing transaction visibility on a user basis.
Multi-channel collection: Receiving remote payments via methods such as payment links, SMS, email, or QR codes.
Reporting: Monitoring collection transactions, payment statuses, and relevant financial data more easily.
ERP and accounting integration: Ensuring that collection data is transferred to relevant financial systems within the scope of suitable integrations.
Cancellation and refund processes: Managing cancellation and refund processes for supported transactions through the system.
These features can reduce the business's need to switch between different tools during its collection processes. Especially for companies with an extensive dealer network, regular collections, or a high number of current accounts to manage, an online collection system holds value not just as a payment channel, but as an operational management tool.
Key Differences Between Virtual POS and an Online Collection System
The easiest way to understand the difference between the two solutions is to separate the payment itself from the operations conducted around the payment.
Virtual POS focuses on executing the card payment transaction. Depending on the features it offers, an online collection system can link this transaction with customer, dealer, current account, reporting, and accounting processes.
Comparison
Feature | Virtual POS | Online Collection System |
Primary purpose | Taking card payments | Managing collection transactions and related operations |
Taking payments | Offers card payment infrastructure | Can facilitate collections via integrated payment infrastructures and other supported channels |
Multiple POS management | Depends on the provider and integration | Can provide central management through multi-POS integration |
Dealer and customer tracking | May require additional integration or software | Can support customer and dealer-oriented collection management |
Payment links & alternative channels | Varies according to the service provided | Can combine channels like links, SMS, email, and QR codes |
Reporting | May offer transaction reports | Can provide more comprehensive tracking and reporting tailored to collection operations |
ERP and accounting integration | May be possible with a separate integration | Can ensure collection data is transferred to financial systems via supported integrations |
Operational scope | Payment acceptance-centric | Can handle payment collection and collection management together |
There is an important detail here: Not every virtual POS only provides basic transaction information; some providers may also offer advanced reporting and integration features. Similarly, not every online collection system provides all the features in the table as standard. When making a comparison, the actual scope of the product and the needs of the business should be considered.
Why Might Taking Payments Alone Not Be Enough?
Imagine a wholesale company making regular collections from 200 dealers in different cities. The company can receive payments from its dealers via virtual POS. At first glance, the process seems flawless: the payment is made, and the transaction is completed.
However, the finance team still has questions that need answering. Which dealer does the incoming payment belong to? Which invoice or open debt of the dealer was cleared? How did the payment reflect on bank records? Was the current account in the accounting system updated?
If the answers to these questions are being searched for across different bank screens, in emails, or in Excel files, the collection operation may not have become as easy as the payment process itself.
Moreover, as the number of transactions increases, checking every payment, matching it with the correct record, and transferring it to the accounting system can require much more time. Repeated manual data entries can also increase the risk of errors.
This is where the difference of an online collection system emerges. Associating the collection with the relevant customer or dealer, tracking transactions centrally, and transferring them to accounting processes through appropriate integrations can help reduce the operational burden on the finance team.
The goal is not just to execute the payment, but to make the financial data generated after the payment usable.
What Features Differentiate Netahsilat from Virtual POS?
Finrota's online collection solution, Netahsilat, supports businesses in collecting from dealers, sub-dealers, and customers; and managing different payment infrastructures, collection channels, and financial systems all together.
The standout aspect of Netahsilat is that it treats virtual POS integration as part of a more comprehensive collection management structure. The main features that businesses can evaluate according to their needs are as follows:
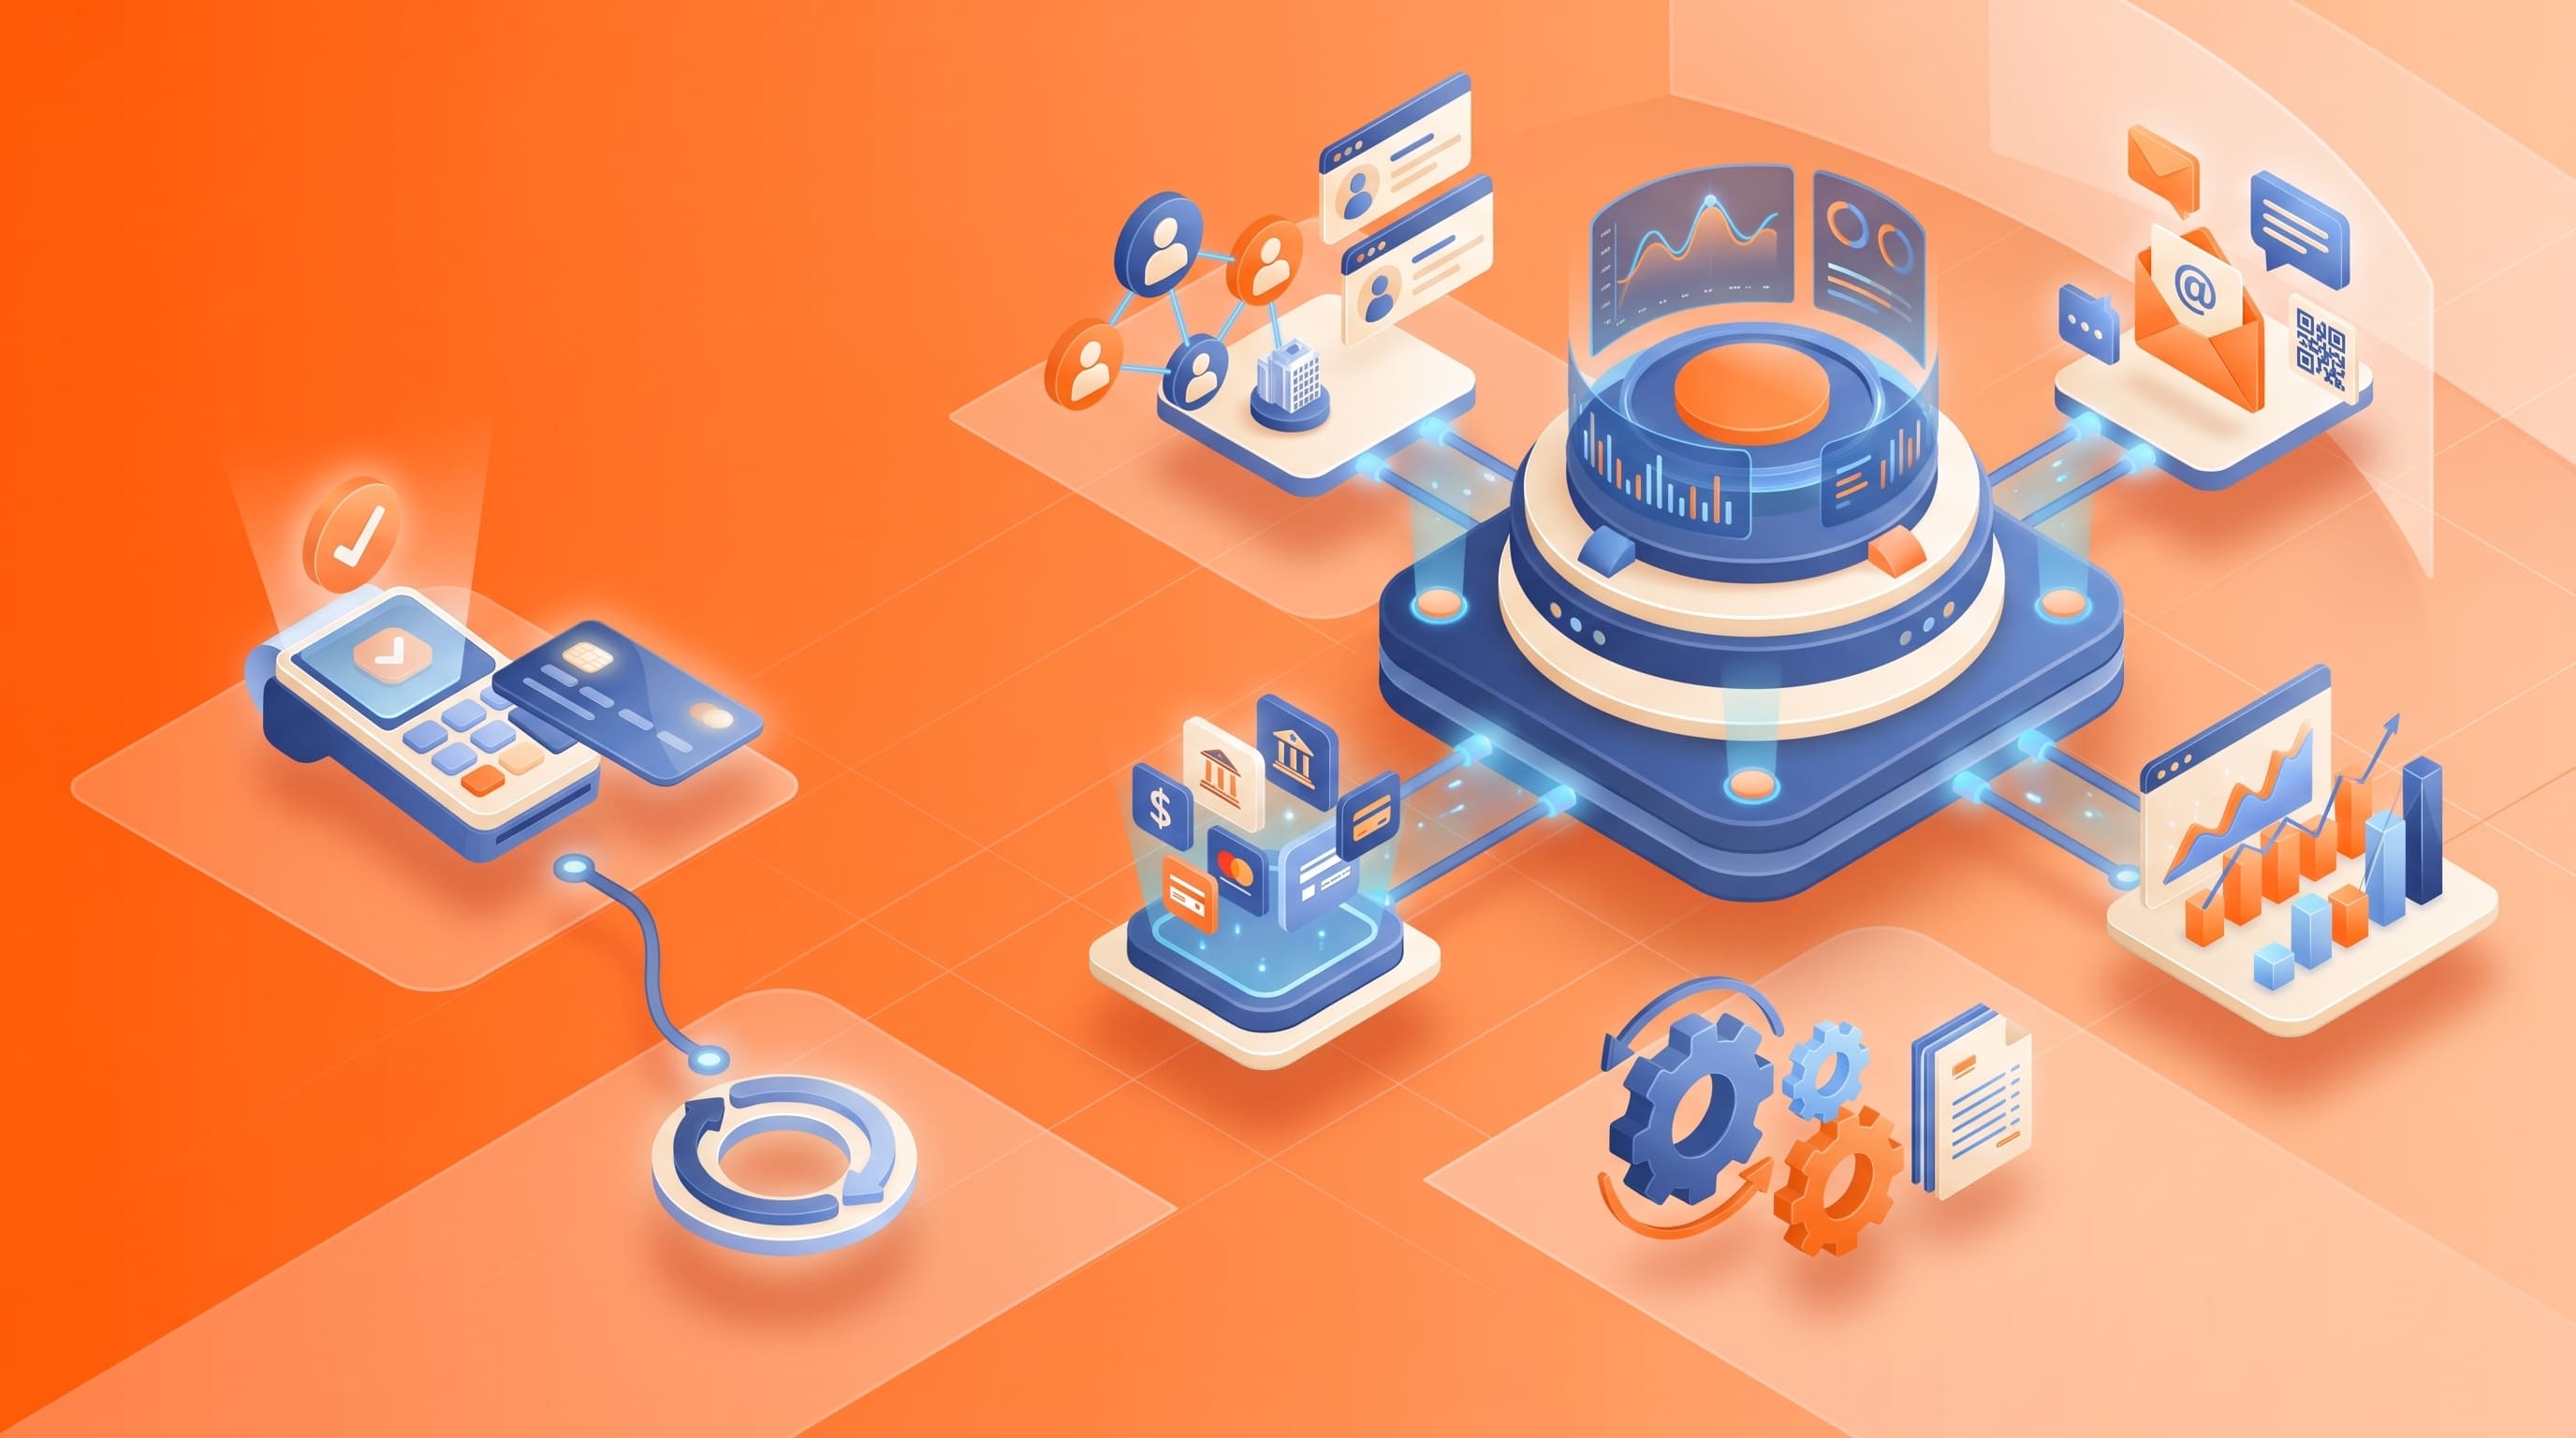
1. Managing Multiple Virtual POS in a Single Structure Businesses working with multiple banks or payment institutions may have to track different POS infrastructures. Managing each infrastructure separately can increase the complexity of operations. Netahsilat supports multiple virtual POS integrations, allowing businesses to bring different payment infrastructures together in a centralized collection structure. Thus, businesses can use the integrations that suit their needs through a single platform.
2. Sending Payment Links via SMS, Email, and QR Code It is not necessary to wait for the customer to visit the business's website or reach a physical payment point for every collection. Using methods supported via Netahsilat, a payment link can be generated and sent to the customer via SMS, email, or QR code. The customer can proceed to the payment step via the provided link. This method offers a practical alternative for businesses that sell remotely, provide field services, or collect regular payments from their customers.
3. Centralized Tracking of Dealer, Sub-Dealer, and Customer Collections For businesses with a dealer network, merely knowing the collection amount may not be enough. It is also important to know which dealer the payment came from and how the related commercial relationship will be tracked. Netahsilat supports the management of collection processes through dealer and sub-dealer structures. Payment processes for relevant parties can be executed based on defined users and permissions.
4. Integration with ERP and Accounting Systems One of the most crucial steps in the collection process is ensuring that the received payment accurately reflects on the business's financial records. Netahsilat can ensure that collection data is transferred to relevant systems through supported ERP and accounting integrations. Options for integration with systems like SAP and Logo are also included in Finrota's product details.
5. Remote and Field Collections with Mobile Devices Collection transactions do not always take place in the office or on a website. Field teams, sales representatives, and dealer managers may also need to take payments from customers. Thanks to Netahsilat's mobile usage options, in supported scenarios, collections can be made via a smartphone or tablet without the need for a physical POS device.
6. Foreign Currency Collection Options For businesses that have commercial relationships abroad or need to collect in different currencies, foreign currency payment options are essential. Netahsilat supports collections in USD, EUR, and other foreign currencies alongside the Turkish Lira, within the scope of supported currencies.
7. Security and Business-Specific Configuration In financial transactions, security is a fundamental issue that must be evaluated independently of the payment method. Netahsilat's product page specifies PCI DSS, ISO 27001, and 3D Secure support. In addition to these security elements, businesses should also evaluate user authorization, transaction tracking, and configuration options suitable for their internal processes.
For Which Businesses is an Online Collection System More Suitable?
When choosing between a virtual POS and an online collection system, it is necessary to evaluate the business's current needs alongside the operational requirements that may arise as it grows.
Virtual POS may be more suitable if:
The basic need is to take card payments over the internet.
Transaction volume and customer structure are easily manageable.
Collection tracking and accounting processes are adequately handled with existing systems.
An online collection system may be more meaningful if:
Collections are made from a large number of dealers, sub-dealers, customers, or subscribers.
You are working with multiple banks or payment institutions.
Different collection channels are needed, such as payment links, SMS, emails, or QR codes.
Collections need to be tracked on a customer, dealer, or current account basis.
Collection data needs to be transferred to ERP or accounting systems.
The finance team is losing time between different screens, files, and manual checks.
There is no single right choice here. The collection methods, transaction frequency, dealer network, and existing financial software impact the decision as much as the size of the business.
Virtual POS or Online Collection System? What to Consider When Deciding?
Before choosing a solution, looking solely at the payment processing cost or supported cards may not be sufficient. How the collection will be managed from pre-payment to accounting entry must also be evaluated.
The following questions can guide you when making a decision:
Do I need to use the virtual POS infrastructure of multiple banks or payment institutions?
Can I track collections from my dealers and customers on a single screen?
Do I need alternative methods like payment links or mobile collections?
Is my collection data being transferred to my accounting or ERP system?
How am I managing cancellation, refund, and reporting processes?
When my transaction volume increases, will the current structure continue to meet my operational needs?
Conclusion: Taking Payments and Managing Collections Are Not the Same Thing
The main difference between a virtual POS and an online collection system relates to where the business's needs begin and end. While a virtual POS enables the execution of a card payment transaction, an online collection system—depending on the features it offers—can combine this transaction with processes like customer and dealer tracking, reporting, and accounting integration.
Finrota Netahsilat treats receiving payments as only one step of the collection operation. By bringing together multi-virtual POS integration, different collection channels, dealer and customer management, and ERP integration options, it helps businesses manage their collection processes in a more centralized and traceable structure.
If your business's need is solely to accept card payments online, a virtual POS may be sufficient. However, if you want to track collections centrally, organize dealer and customer processes, and establish links with financial records, a comprehensive online collection system like Netahsilat is among the solutions you can evaluate.
Request a demo today to see Netahsilat’s ERP integration and dealer management screens live.